California reduces bearing acreage for the first time since 1995, Australia faces a “generational” rainfall event, and Spain posts a record 146,000-ton crop. India and China emerge as consumption engines, while GLP-1 drugs and food reformulation create new opportunities for the sector.
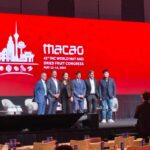
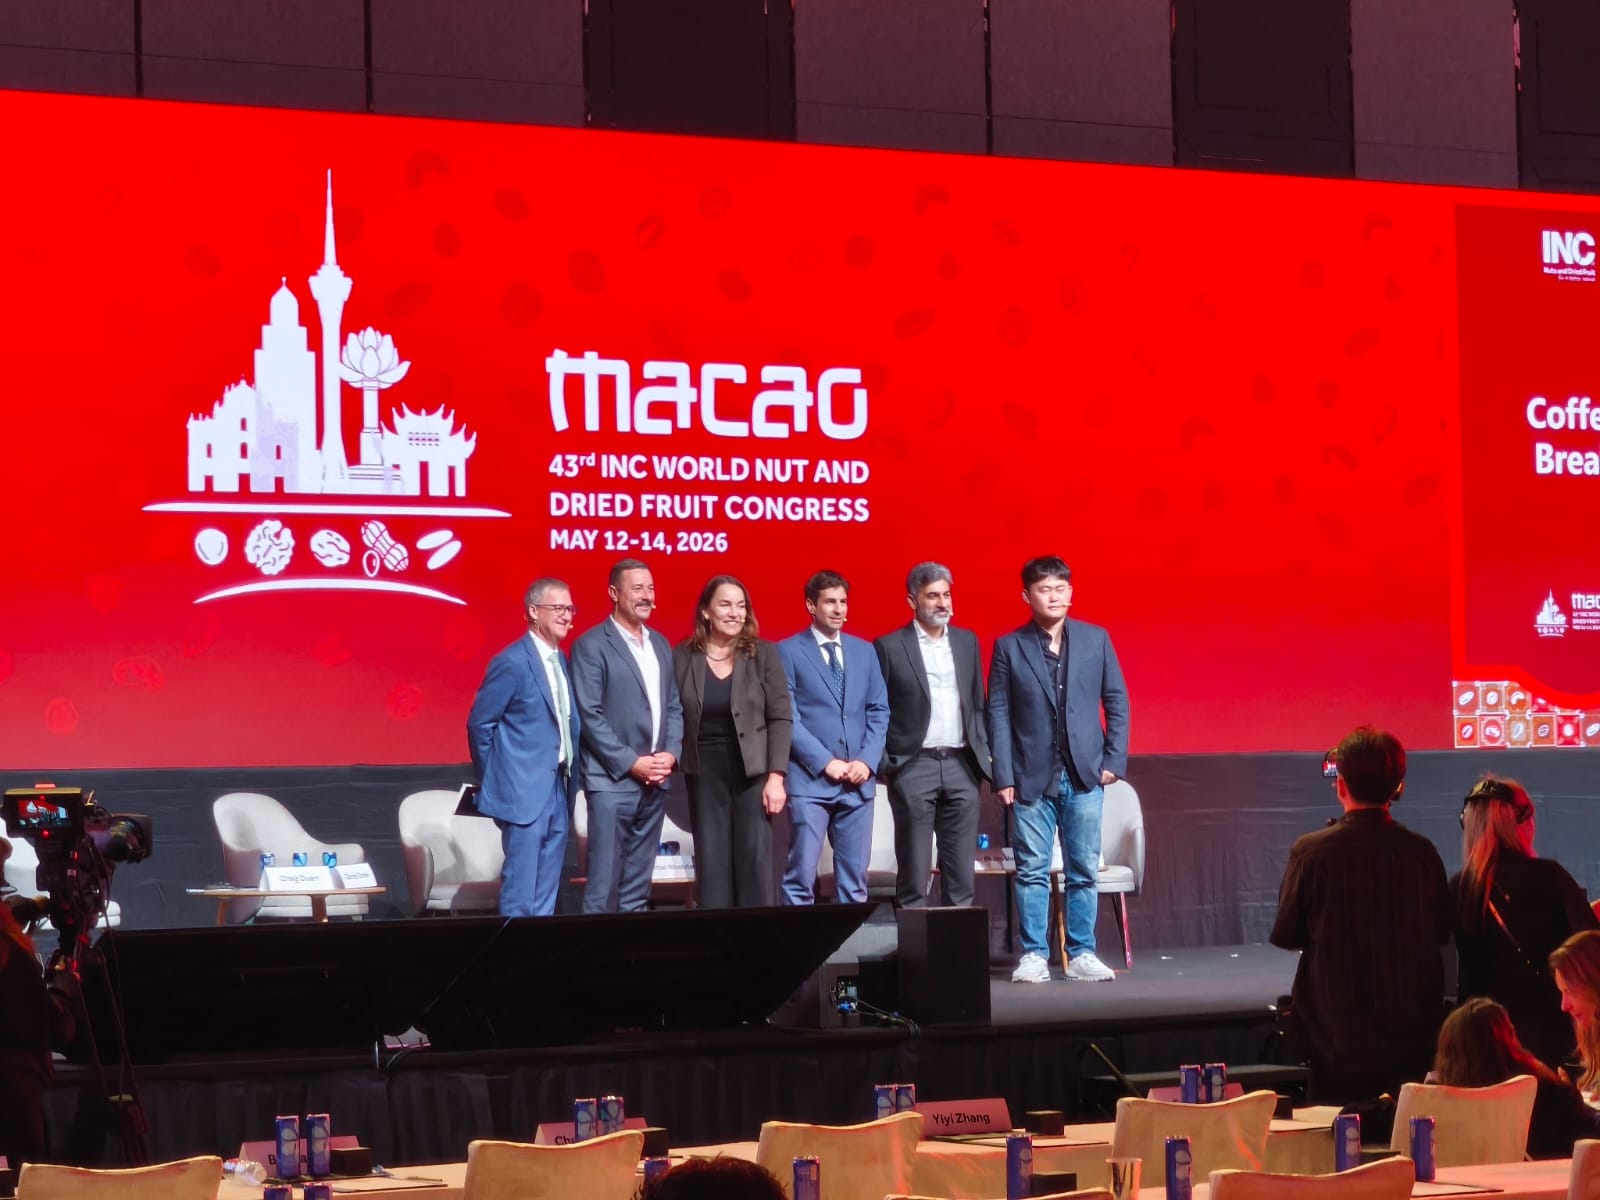
MACAU. — Producers and marketers from the world’s leading almond origins agreed during the International Nut and Dried Fruit Council (INC) roundtable that global almond supply and demand are beginning to rebalance for the first time in years, as cost pressures and rapidly evolving consumer behavior reshape the industry.
The United States, the Iberian Peninsula, and Australia currently account for nearly 91% of global almond supply. However, the industry projects a net decline of approximately 100 million pounds by 2030, driven primarily by California, while the rest of the world is expected to grow at close to 3%.
California: structural adjustment
For the first time since 1995, California’s bearing almond acreage declined, while total planted area has now fallen for four consecutive years, according to Craig Duerr, Vice President of Global Sales and Marketing at Campos Brothers Farms (United States).
The industry expects crops ranging between 2.6 and 2.8 billion pounds over the next five to six years.
Three key factors explain this adjustment. The first is the implementation of the Sustainable Groundwater Management Act (SGMA), which regulates groundwater use and particularly affects growers located in “white areas” dependent exclusively on well water, representing about 17% of the crop.
This is compounded by rising production costs, including fertilizers and phosphorus — the latter affected by geopolitical tensions in the Middle East — as well as increasing competition for land from pistachios, citrus, and olives.
As a result, return on investment has extended from four to five years to a seven- to eight-year horizon.
Australia: climate shocks and water pressure
Brenton Woolston, Managing Director of Almondco (Australia), described the season as being hit by a “generational rainfall event” that affected product quality and slowed harvest progress.
Although yields are expected to recover in 2026, the water outlook remains challenging. Water from the Murray-Darling system is projected to be scarce and expensive, with additional pressure from competition with rice and cotton production.
In addition, more than 50% of Australia’s orchards will need renewal before 2030.
Spain: record crop and production optimism
Antonio Mejías, Key Account Manager at DCOOP (Spain), highlighted a historic crop of 146,000 metric tons, supported by a cold winter with sufficient chill hours and rainfall that replenished reservoirs for two to three years.
The Lauranne and Vairo varieties stood out for their productivity, with some branches reportedly breaking under the weight of the crop.
In contrast, frost events in Granada and Almería reduced the supply of organic almonds, a segment expected to see higher prices.
Spain projects production between 175,000 and 200,000 metric tons by 2028, in what Mejías described as “a turning point” for the industry.
Global consumption in transition
India is emerging as one of the world’s most dynamic almond markets. The depreciation of the rupee — from 50 to 95 per U.S. dollar since 2014 — combined with extremely tight margins across the supply chain (1%–2% for importers and 5%–10% for retail), has resulted in almonds being sold at lower prices today than a decade ago.
Even so, the market continues to grow at high double-digit rates and could surpass the United States as the world’s largest almond consumer.
In China, market value demand has grown 5% over the past two years, driven by urban bakery consumption and retail chains such as Sam’s Club and Costco incorporating products positioned around glycemic index benefits.
The United States, by contrast, faces a different landscape. Food inflation has reached 28.4% since 2021, while GLP-1 medications — increasingly used for weight management and diabetes treatment — are rapidly reshaping consumption patterns.
According to figures presented at the panel, households with at least one GLP-1 user increased from 11% in 2023 to 16% in 2024, with projections reaching 35% by 2030.
Food reformulation and emerging uses
Panelists agreed that almonds are well positioned within the global food reformulation trend, thanks to their high nutritional density, protein and fiber content, low sugar levels, and actual caloric absorption that could be up to 30% lower than declared on labels, according to ongoing research.
Emerging studies were also cited around topical applications linked to retinol, antioxidants, and acne treatment.
Another major opportunity lies in byproduct valorization, particularly almond hulls, which represent approximately 30% of the fruit and are estimated to hold a potential U.S. market of 4 billion pounds annually as a source of fiber and natural sugars.
“We have more challenges than opportunities; collaboration among producing origins will be critical,” concluded Clarice Turner, President and CEO of the Almond Board of California, closing a session that portrayed an industry undergoing rapid transformation amid climate change, regulatory pressure, and fast-evolving global consumer behavior.