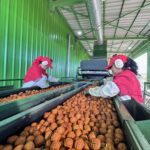

The U.S. pecan industry closed the 2025 season with a recovery in production, although within a context of greater commercial pressure and mixed quality outcomes.
According to the USDA National Agricultural Statistics Service (NASS), the crop reached approximately 270–300 million pounds, surpassing the previous cycle and reflecting a rebound after a weaker 2024 season.
From an industry perspective, the American Pecan Council noted that the increase in volume was accompanied by variability in nut sizes, due to fluctuating weather conditions —including heat episodes and water stress— that affected fruit development in some regions. This is compounded by a structural characteristic of the crop: pecan trees naturally alternate between years of lower and higher production, which partly explains the recovery seen in 2025.
On the commercial side, the higher U.S. output, combined with Mexican supply, has led to high global availability, putting downward pressure on prices, particularly for mid-sized grades. According to the American Pecan Council, international demand remains active, but is more selective and increasingly sensitive to price and quality.
In this context, markets such as China continue to play a key role in balancing the sector, although with more cautious purchasing patterns, according to reports from the USDA Foreign Agricultural Service.
In summary, the 2025 season confirmed a higher production scenario, but also highlighted the challenges of a more competitive market, where quality, sizing, and commercial efficiency will be key to sustaining industry profitability.