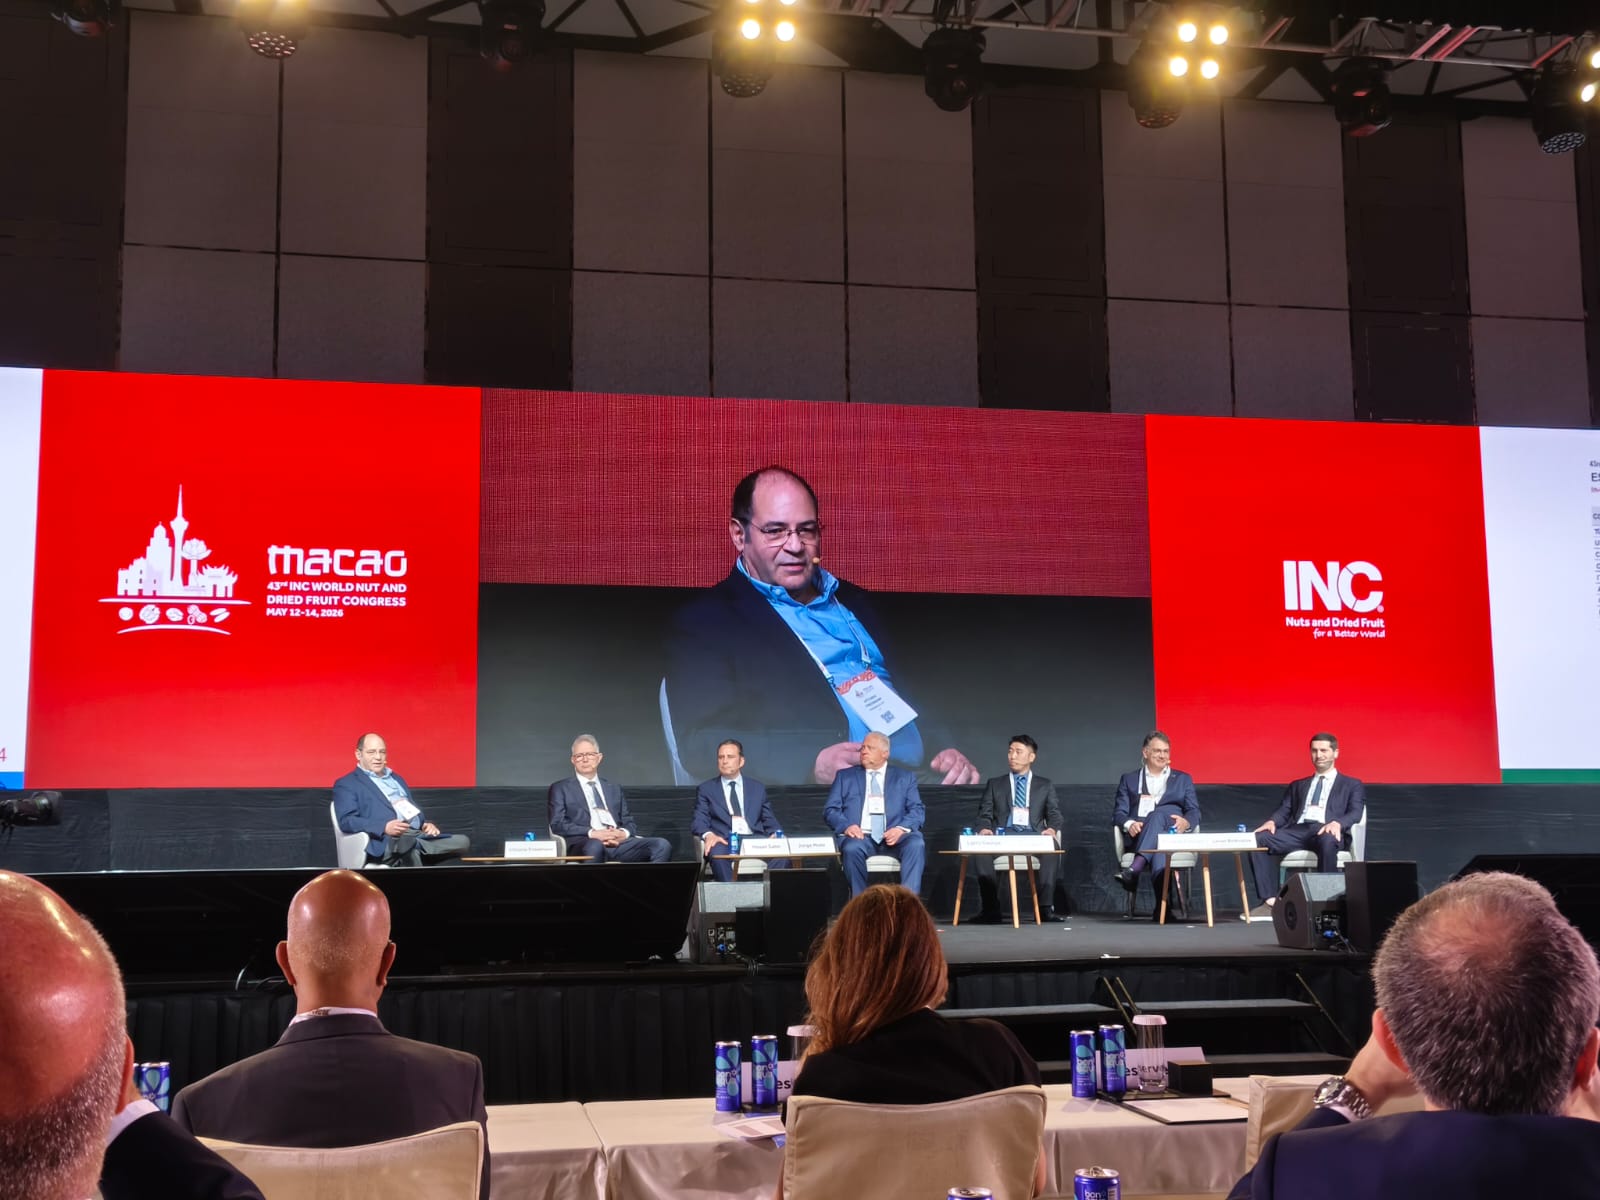
The INC Hazelnut Roundtable in Macau sent a clear signal: the global market is moving toward a structure less dependent on Turkey. While the world’s leading producer remains dominant, soaring costs, phytosanitary pressure, and demand overly concentrated in confectionery are accelerating a structural transformation of the industry.
MACAU. — The global hazelnut industry is undergoing one of its most profound transformations in decades. With worldwide production estimated at 1.08 million metric tons in-shell for the 2025/26 season, and projections pointing to a 33% increase for 2026/27, expanding supply stands in contrast to growing concerns over the industry’s economic sustainability and the concentration of demand.
The most significant shift is geographic.
Turkey, historically synonymous with hazelnuts, now accounts for roughly 49% of global production—a substantial share, but significantly below the near-monopolistic dominance it maintained for years. The 2025/26 crop was estimated at 518,000 metric tons in-shell, far below the ambitious projections of 850,000 to 1 million metric tons that the industry itself anticipated more than a decade ago.
“Comparatively, climate conditions this year were much, much better,” said Hasan Sabir, General Manager of Sabirlar, during the panel discussion. However, he warned that the impact of the brown marmorated stink bug (BMSB) and global warming continues to constrain production potential, particularly in Turkey’s coastal growing regions.
Adding to the pressure is a severe economic challenge. Between January 2022 and May 2026, Turkey’s minimum wage increased by 560%, while inflation rose 428%. Although the U.S. dollar also appreciated against the Turkish lira, the currency mismatch dramatically increased real production costs, eroding export competitiveness without proportionally improving grower income.
Chile and the U.S. strengthen their position
As Turkey loses relative weight, Pacific producers are gaining momentum.
Chile has emerged as one of the biggest winners of this new cycle. The country expanded from 20,000 hectares in 2014 to approximately 70,000 today, with projections reaching 90,000 hectares by 2030. More importantly, average yields of 3.5 to 4 metric tons per hectare far exceed Turkish levels, supported by highly mechanized production systems and competitive cost structures.
In the United States, particularly Oregon and Washington, the industry has also established itself as a structural player, with production reaching 110,000 metric tons.
Larry George, President of George Packing Company, summarized the sector’s economic logic clearly: above US$8,500 per metric ton CIF Europe, new plantings are triggered; below US$8,200, grower enthusiasm fades.
The strategic advantage of both origins is evident: they provide complementary supply to the Northern Hemisphere, improving year-round availability of high-quality product.
The real risk lies in demand
While supply is becoming more diversified, demand remains dangerously concentrated.
Currently, 75% of global hazelnut consumption depends on the confectionery sector—primarily chocolates, coatings, and spreads—leaving limited room for categories such as snacks, bakery, cereals, or ice cream.
That dependency became evident during the high-price cycle of 2024–2025, when snack demand softened and some markets reduced purchases.
In addition, hazelnuts face direct competition from more versatile and competitively priced tree nuts, such as almonds and cashews, limiting their natural expansion beyond confectionery applications.
India, China, and the next frontier
The industry is already working on its next growth phase.
India has emerged as a priority growth market for Turkey, although the starting point remains modest: Turkish exports to India grew 172% in volume between 2020 and 2025, but remain marginal compared to the roughly 190,000 metric tons of California almonds imported annually by India.
Meanwhile, China continues to establish itself as a relevant future producer, reinforcing the view that the global hazelnut map will become increasingly less dependent on a single origin.
An irreversible reconfiguration
The panel’s conclusion was unequivocal: the hazelnut industry has entered a new phase.
More than a supply issue, the structural challenge lies in building a more diversified and resilient demand base. As new producers gain market share, a market excessively dependent on a single segment remains the industry’s greatest long-term vulnerability.
Source: Hazelnut Roundtable, 43rd INC World Nut and Dried Fruit Congress, Macau (May 12–14, 2026).